Small Business Taxes for LLC Owners: The Complete 2026 Guide
Small business taxes for LLC owners in 2026: self-employment tax, the QBI deduction, four new Schedule 1-A deductions, quarterly payments, and deadlines.
Finance
The 2026 1099-K threshold is $20,000 and 200 transactions, but nine states set it far lower and no form never means no tax. Full rules for resellers.

The federal 1099-K threshold for 2026 is $20,000 in payments and more than 200 transactions. Both conditions have to be true. Sell $30,000 across 120 transactions and no federal form arrives. Sell $9,000 across 400 transactions and no federal form arrives either. Only crossing both lines triggers one.
None of that changes what you owe. The 1099-K threshold governs when a platform must report your payments to the IRS, not whether the money is taxable. Every dollar of profit from reselling, freelancing, or gig work belongs on your return whether a form shows up or not. And if you live in one of nine states with a lower threshold, a form may arrive regardless of what the federal rule says.
The One Big Beautiful Bill repealed the lower limits that had been scheduled and retroactively restored the original rule for 2025 and 2026. Platforms including eBay, Poshmark, Mercari, Depop, Etsy, StubHub, PayPal, and Venmo apply it to goods and services payments.
Personal transfers never counted. Splitting rent, repaying a friend, or sending a birthday gift through Venmo stays outside the 1099-K threshold entirely, as long as the sender marks it correctly.
Platforms apply the lower of the federal or state rule based on your address. A seller in Vermont clearing $800 across a dozen sales receives a 1099-K while an identical seller in Florida receives nothing, and neither situation changes the tax owed.
Illinois works differently from the rest. Rather than a flat dollar figure, it requires four or more transactions totaling more than $1,000, so a seller who moves three expensive items stays outside it.
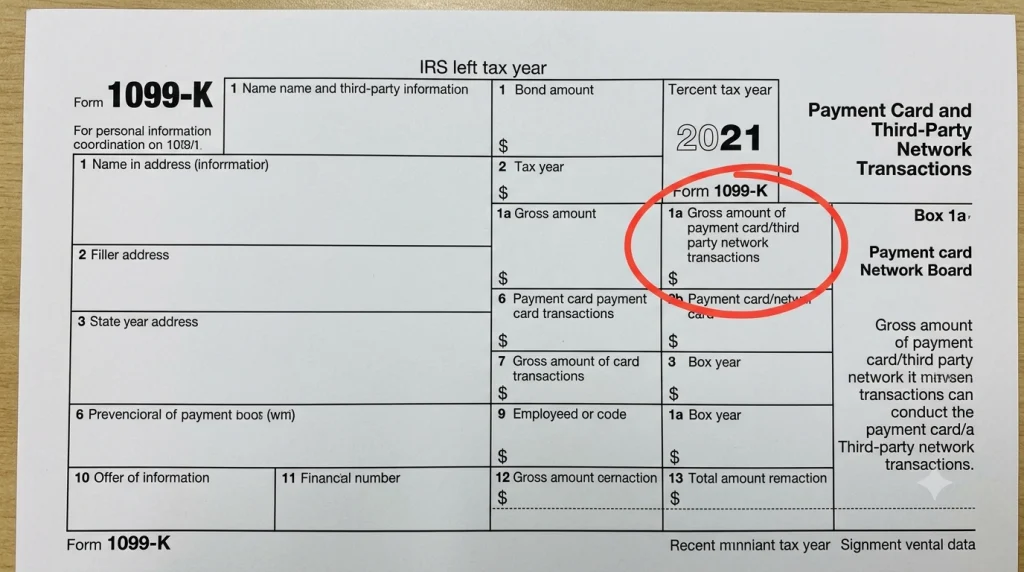
This is the misconception the 1099-K threshold creates every year. The form is an information return. It tells the IRS what a platform paid you. Its absence tells the IRS nothing and excuses nothing.
A reseller earning $8,000 of profit across 90 sales owes tax on that profit, files a Schedule C, and pays self-employment tax on it, all without ever seeing a 1099-K. Sizing that obligation is the job of our guide to how much to set aside for taxes, and the payments themselves run through quarterly estimated taxes once you expect to owe $1,000 or more.
The practical risk of assuming otherwise is compounding. Skip a year of unreported reselling profit and you accumulate tax, an underpayment penalty, and interest, all discovered later when a form finally does arrive and the IRS matches prior patterns.
A 1099-K reports gross payments before anything comes out. Platform commissions, payment processing, shipping labels, packaging, mileage to the post office, and above all the cost of the inventory itself all reduce it.
The reseller above pays tax on $5,300, not $24,000. Sellers who see a five-figure form and panic usually have not subtracted what they paid for the goods, which is often the largest number on the page.
Keeping that documentation is the whole game. Receipts for sourced inventory, monthly platform fee statements, and shipping records turn a scary gross figure into a defensible profit figure.
Cleaning out a closet is not a business. Selling a $900 couch for $300 produces a loss, and personal-use losses are neither deductible nor taxable.
The complication comes when a 1099-K arrives anyway, which happens easily in a $600-threshold state. The IRS expects the form’s figure to appear on your return, so you report it and back it out: enter the proceeds on Schedule 1 as other income, then enter an offsetting negative amount on the same schedule describing it as the cost of personal property sold. Net effect zero, and the matching program stays satisfied.
Selling personal items at a profit works differently. A collectible bought for $200 and sold for $1,500 produces a $1,300 capital gain that belongs on Schedule D.
Consistent buying to resell makes you a business, which means Schedule C, self-employment tax, and full expense deductions. Occasional decluttering does not.
The IRS weighs whether you operate in a businesslike manner, depend on the income, keep records, and pursue profit. Sourcing inventory weekly and listing 200 items a year lands squarely on the business side, which is better news than it sounds: businesses deduct expenses, and hobbies no longer can.
Gig drivers and delivery couriers sit in the same category, and those in tipped roles should check whether no tax on tips applies to their customer tips.
Freelancers get their own change this year. The reporting threshold for Form 1099-NEC and 1099-MISC rose from $600 to $2,000 for payments made on or after January 1, 2026, and it indexes for inflation in $100 increments starting in 2027.
A consultant paid $1,500 by a client in 2026 receives no form. The client has no filing obligation. The consultant still owes tax on all $1,500.
Business owners paying contractors should update their systems now, because the old $600 trigger is wrong for 2026 payments and filing unnecessary forms creates reconciliation work nobody needs.
$20,000 in gross payments and more than 200 transactions at the federal level. Both must be exceeded for a platform to issue a form.
Yes. The 1099-K threshold determines reporting by the platform, not taxability. All profit is reportable regardless.
DC, Maryland, Massachusetts, Montana, North Carolina, Vermont, and Virginia use $600. New Jersey uses $1,000, Illinois requires four or more sales over $1,000, and Missouri uses $1,200.
No. It reports gross payments before inventory cost, platform fees, and shipping. Your taxable figure is what remains after those.
Report the 1099-K proceeds on Schedule 1 and enter an offsetting negative amount for the cost of personal property sold. The loss itself is not deductible.
Yes. It rose from $600 to $2,000 for payments made on or after January 1, 2026, indexed for inflation from 2027.
No. Only goods and services payments count toward the 1099-K threshold. Personal transfers are excluded when marked correctly.
Sources: IRS, understanding your Form 1099-K · IRS, what to do with Form 1099-K · Thomson Reuters, state reporting changes for 2026 · OnPay, 1099 threshold updates under OBBBA
Related
Small business taxes for LLC owners in 2026: self-employment tax, the QBI deduction, four new Schedule 1-A deductions, quarterly payments, and deadlines.
Self-employed health insurance in 2027: premiums up 14%, the returning subsidy cliff at 400% FPL, and the deduction rule your spouse's job can disqualify.
Quarterly estimated taxes for 2026: the September 15 deadline, safe harbor rules, what the penalty really costs, and how new deductions change your payment.

